Updated: August 23, 2026
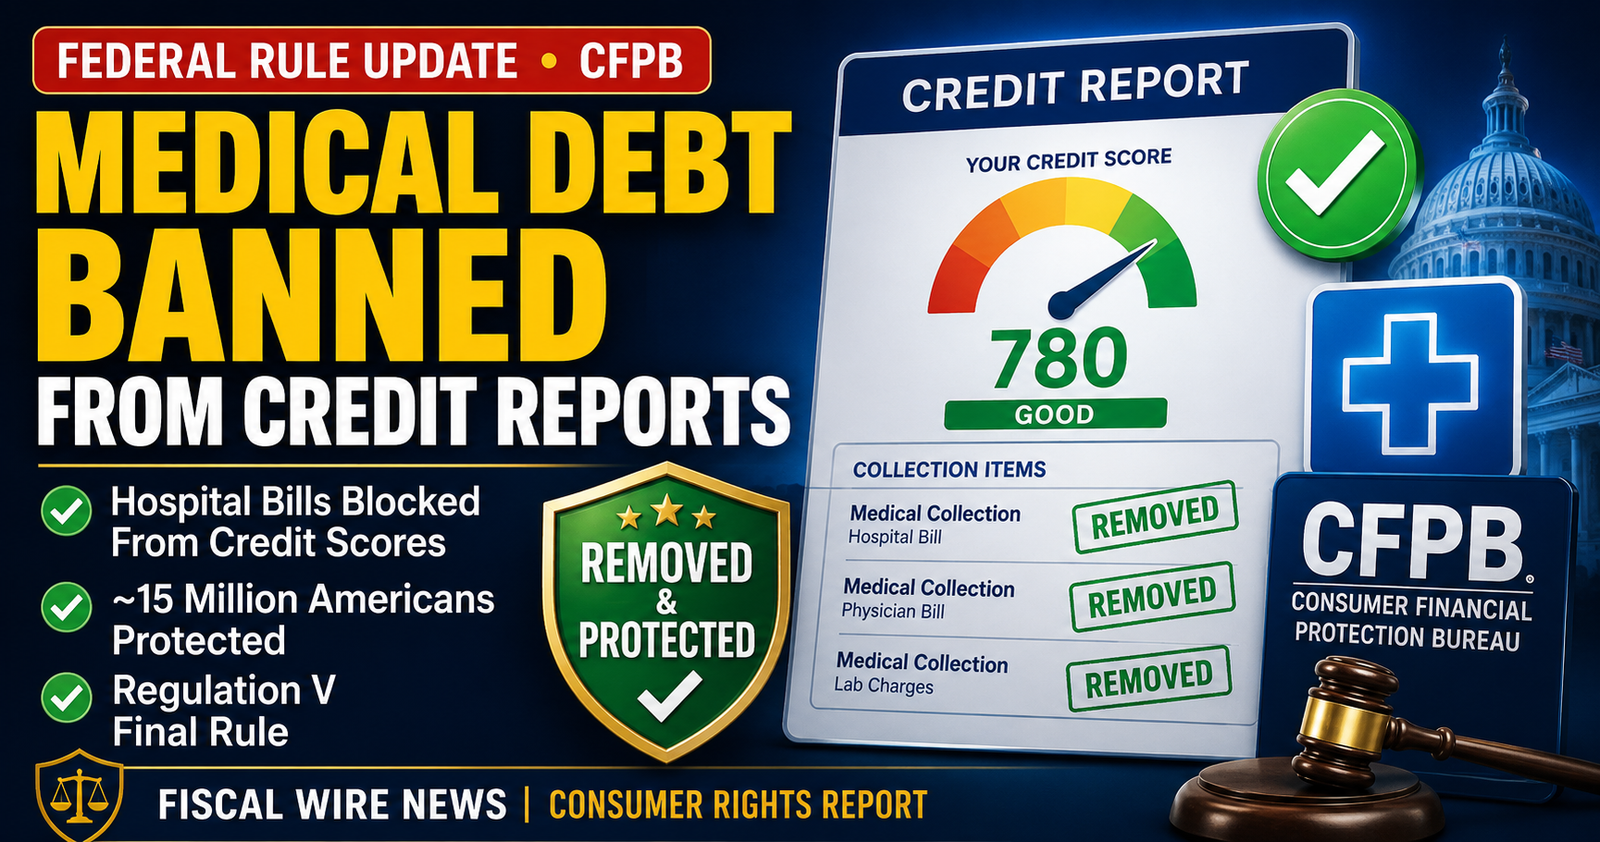
A federal CFPB rule that would have broadly removed medical debt from credit reports was vacated by a federal court in July 2025. Medical debt has not disappeared from credit reporting entirely, but consumers still have important protections involving paid collections, smaller balances, reporting delays, billing accuracy, and disputes.
Key Facts
- The CFPB’s 2025 medical-debt credit reporting rule was vacated by the U.S. District Court for the Eastern District of Texas on July 11, 2025.
- Current CFPB guidance says unpaid medical debt that is more than 365 days delinquent and over $500 may appear on a credit report.
- The three nationwide credit reporting companies previously adopted voluntary policies removing paid medical collections and medical collections below $500 from consumer credit reports.
- Consumers can dispute inaccurate medical-debt information under the Fair Credit Reporting Act.
- A credit-reporting restriction does not erase a valid medical bill or automatically prevent lawful collection activity.
What Happened to the CFPB Medical Debt Rule
The Consumer Financial Protection Bureau finalized a rule in January 2025 that would have restricted creditors from using certain medical-debt information and would have limited its appearance in consumer reports used for lending decisions.
That rule is no longer in effect. On July 11, 2025, the U.S. District Court for the Eastern District of Texas vacated it in Cornerstone Credit Union League v. CFPB. The CFPB now states that the court concluded the rule exceeded the Bureau’s authority under the Fair Credit Reporting Act.
The CFPB’s current Regulation V page identifies the rule as vacated. The Bureau also says its older materials about the medical-debt rule are now available for reference rather than as an operative federal requirement.
Can Medical Debt Still Appear on a Credit Report?
Yes, in some circumstances.
Current CFPB guidance says unpaid medical debt that is more than 365 days delinquent from the date of service and has a balance above $500 may appear on a consumer’s credit report.
That is different from saying all medical debt is reportable. The nationwide credit reporting companies adopted voluntary medical-collection policies before the CFPB’s later federal rule.
Those policies generally removed paid medical collections, delayed reporting of unpaid medical collections for one year, and removed medical collections with original balances below $500.
Consumers can review the CFPB’s current guidance on medical bills and credit reports for the latest federal consumer information.
What Protections Still Apply
The court’s decision did not eliminate the Fair Credit Reporting Act or other consumer protections involving inaccurate medical-debt information.
Credit reporting companies are still required to follow reasonable procedures designed to assure maximum possible accuracy. Consumers also have the right to dispute information they believe is inaccurate or incomplete.
Medical debt may also involve protections under the No Surprises Act. The CFPB says debt collectors and credit reporting companies may violate federal law if they attempt to collect or report amounts that exceed what a consumer is legally required to pay under applicable surprise-billing protections.
The CFPB explains these protections in its medical debt collection and credit reporting guidance.
What Changed — and What Did Not
- What changed: The broad CFPB rule finalized in January 2025 was vacated and cannot be treated as the current nationwide federal standard.
- What remains: Paid medical collections and many low-balance medical collections may still be excluded under voluntary nationwide credit-bureau policies.
- What remains: Some unpaid medical collections over $500 that are more than one year old may still appear on credit reports.
- What remains: Consumers can dispute inaccurate or invalid information under federal credit-reporting law.
- What does not change: Removing or excluding a medical collection from a credit report does not automatically cancel a valid medical debt.
What Consumers Should Do Now
- Check all three credit reports. Use AnnualCreditReport.com, the federally authorized source for free credit reports.
- Review any medical collection carefully. Check the balance, provider, date of service, payment status, and whether the collection is more than one year old.
- Dispute inaccurate information. If a medical collection is paid, duplicated, belongs to someone else, contains the wrong balance, or otherwise appears inaccurate, dispute it with the credit reporting company.
- Verify the underlying bill. Ask the healthcare provider for an itemized statement if you do not recognize the charge or believe insurance should have paid more.
- Check for financial assistance. Nonprofit hospitals may offer financial-assistance or charity-care programs. Eligibility varies by institution and household circumstances.
- Use official complaint channels when needed. Consumers having problems with credit reporting or debt collection can use the CFPB consumer complaint portal.
Medical Credit Cards Are Different
One distinction can easily be missed: protections involving medical collections do not necessarily apply to ordinary credit accounts used to pay medical expenses.
If a patient puts a medical bill on a credit card or signs up for a medical financing product, missed payments on that credit account can still affect a credit report. The CFPB specifically warns consumers to review interest rates, deferred-interest terms, and other financing conditions before converting a medical bill into consumer credit.
What the Court Decision Does Not Mean
The court’s decision does not mean medical providers or collectors can report inaccurate information without consequence. Federal credit-reporting and debt-collection laws still apply.
It also does not mean every medical bill above $500 will automatically appear on every credit report. Reporting depends on the status of the debt, the reporting company’s policies, the furnisher, and the applicable legal requirements.
Bottom Line
The headline “medical debt is banned from credit reports” is no longer accurate under current federal law.
The CFPB’s broad 2025 rule was vacated on July 11, 2025. However, important medical-debt protections remain. Paid collections, many lower-balance collections, and newer unpaid medical collections may be excluded under nationwide bureau policies, while consumers retain federal rights to challenge inaccurate reporting.
The safest approach is to check your credit reports, verify any medical collection that appears, dispute errors promptly, and confirm current rules through official CFPB guidance before making financial decisions.
How We Verified This Report
Jurisdiction: United States
Last fact-checked: August 23, 2026
Primary Sources
- CFPB — Consumer Reporting (Regulation V) and court-vacatur status
- CFPB — Current medical bills and credit-report guidance
- CFPB — Medical debt collection and credit reporting protections
Editorial Review
Written and reviewed against current primary sources by Shailendra Singh.
Important Information
This article provides general news and educational information for a U.S. audience. It is not personalized financial, credit, tax, insurance, medical, or legal advice. Rules, reporting practices, and individual circumstances can change.
Official Source Stack
Direct sources supporting the material claims in this report.
- Regulation or statute current Regulation V page
- Official agency release current guidance on medical bills and credit reports
- Official agency release medical debt collection and credit reporting guidance
- Official agency release AnnualCreditReport.com
This report provides general news and educational information for a U.S. audience. It is not individualized financial, credit, legal, tax, insurance or investment advice. Verify current procedures through the linked official sources.