Originally published August 16, 2026; updated August 21, 2026 with Freddie Mac’s August 20 survey.
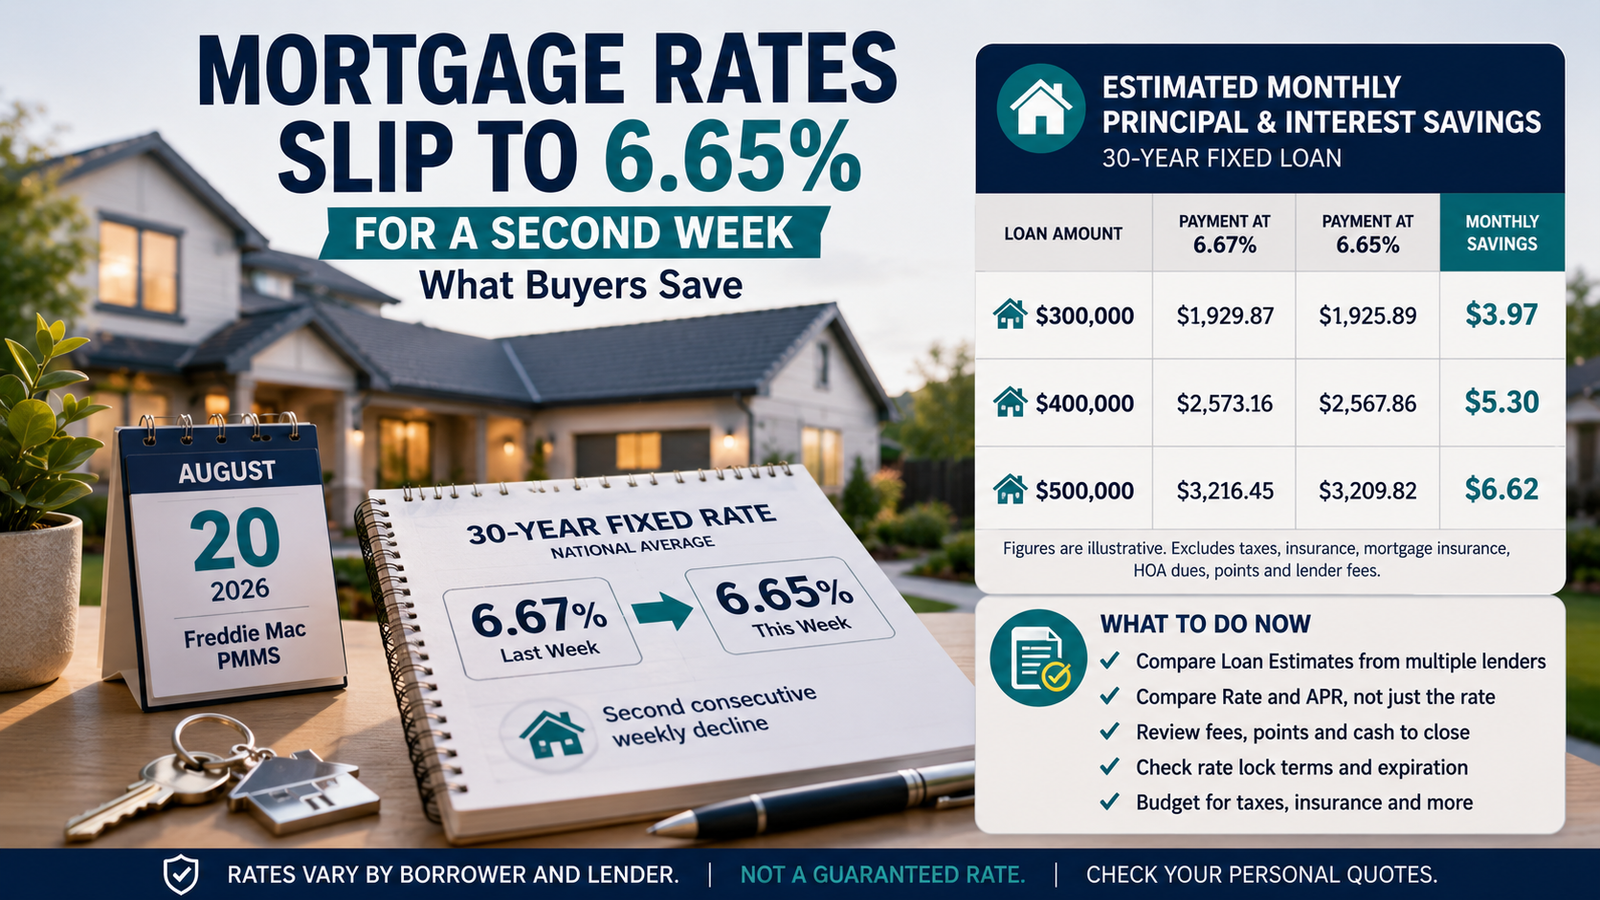
Mortgage rates declined for a second consecutive week, with Freddie Mac’s average 30-year fixed rate falling to 6.65% from 6.67%. The change offers only modest payment relief. On a $400,000, 30-year loan, the difference is about $5.30 per month in principal and interest. The national average is not a rate guaranteed to any borrower.
Key Facts
- The 30-year fixed-rate average was 6.65% as of August 20, down from 6.67% one week earlier.
- The 15-year fixed-rate average edged down to 5.95% from 5.96%.
- The 30-year average remained above its 6.58% reading from the comparable week of 2025.
- Freddie Mac does not publish average points or fees with the current survey.
What the Latest Mortgage Rates Show
Freddie Mac released the latest Primary Mortgage Market Survey on August 20 at noon Eastern Time. The 30-year fixed-rate mortgage averaged 6.65%, two basis points below the previous week.
The latest mortgage rates followed a move from 6.69% on August 6 to 6.67% on August 13. That makes August 20 the second consecutive weekly decrease. The 30-year average was still seven basis points above the 6.58% reading from one year earlier.
The 15-year fixed-rate average fell one basis point to 5.95%. It was 5.69% during the comparable week of 2025, according to Freddie Mac’s weekly mortgage-rate archive.
How Much Does the Drop to 6.65% Save?
The weekly move was small. The table below compares principal-and-interest payments at 6.67% and 6.65% for a 30-year fixed loan.
| Loan amount | Payment at 6.67% | Payment at 6.65% | Monthly difference |
|---|---|---|---|
| $300,000 | $1,929.87 | $1,925.89 | $3.97 |
| $400,000 | $2,573.16 | $2,567.86 | $5.30 |
| $500,000 | $3,216.45 | $3,209.82 | $6.62 |
These calculations assume a fully amortizing 30-year loan with no extra payments. They exclude points, lender fees, mortgage insurance, property taxes, homeowners insurance and association dues. Actual quotes may also use different rounding.
If a $400,000 loan remained in place for all 360 payments, the two-basis-point difference would reduce total interest by about $1,907. Many borrowers sell, refinance or make additional payments before reaching the end of the term, so that lifetime figure is only an illustration.
What Freddie Mac’s 6.65% Average Does Not Mean
Freddie Mac’s figure is a national weekly average, not an advertised offer for every applicant. The survey uses rates from thousands of mortgage applications submitted through its Loan Product Advisor system. Results reflect selected conventional, conforming purchase applications.
The average covers rates offered from the prior Thursday through Wednesday. It does not show a single-day market quote. Freddie Mac also no longer reports average discount points or origination fees, even though both can materially change a mortgage’s cost.
Individual mortgage rates can vary based on credit score, down payment, loan size, property type, occupancy, location and lender pricing. FHA, VA, USDA, jumbo and adjustable-rate loans are not represented by the reported fixed-rate averages.
Who Is Affected by the Weekly Change?
Buyers currently requesting conventional fixed-rate quotes may see slightly better pricing than a week earlier, but lender movement will vary. A two-basis-point national decline alone should not determine whether a household buys a home.
Existing fixed-rate borrowers will not receive a lower payment because the weekly average changed. Refinancing requires a new loan, qualification, closing costs and a borrower-specific break-even calculation.
What Buyers Should Compare Now
- Request written Loan Estimates from multiple lenders for the same loan type, amount and lock period.
- Compare the interest rate and annual percentage rate. APR includes certain points, fees and other borrowing charges.
- Review origination charges, lender credits, cash to close, APR and Total Interest Percentage.
- Ask whether the quote includes discount points and calculate how long recovering their upfront cost may take.
- Confirm whether the rate is locked, when the lock expires and what an extension would cost.
- Budget for taxes, homeowners insurance, mortgage insurance and association dues, not only principal and interest.
The Consumer Financial Protection Bureau provides an official Loan Estimate explainer and a guide to comparing mortgage offers.
The CFPB’s interest-rate and APR guidance explains why the lowest headline rate may not represent the lowest total cost. Its mortgage rate-lock guidance explains how expiration dates and application changes can affect a locked offer.
What Has Not Changed
- The 6.65% average does not alter an existing fixed-rate mortgage contract.
- It does not guarantee that mortgage rates will continue falling next week.
- It does not show whether average points or lender fees became more expensive.
- It does not establish whether buying or refinancing is affordable for a specific household.
Bottom Line
Mortgage rates moved down again, but the change from 6.67% to 6.65% produces limited payment savings by itself. The stronger consumer opportunity is comparison shopping. Buyers should evaluate complete Loan Estimates, including APR, points, fees, insurance and cash to close, rather than relying on the national average alone.
Editorial disclaimer: This article provides general consumer information and illustrative calculations. It is not personalized mortgage, financial, tax, insurance or legal advice. Rates and loan terms vary by borrower and lender.
Official Source Stack
Direct sources supporting the material claims in this report.
- Official agency release Loan Estimate explainer
- Official agency release comparing mortgage offers
- Official agency release interest-rate and APR guidance
- Official agency release mortgage rate-lock guidance
This report provides general news and educational information for a U.S. audience. It is not individualized financial, credit, legal, tax, insurance or investment advice. Verify current procedures through the linked official sources.