Updated
The Nebraska First Street lawsuit challenges property-level climate-risk scores that appear on or are linked from major real-estate listings. Nebraska Attorney General Mike Hilgers alleges that First Street uses inaccurate or incomplete property information in some cases, does not adequately explain model limitations and provides homeowners with an insufficient process for disputing scores. First Street has not been found liable, and the lawsuit does not automatically remove a score, change a property’s FEMA designation or create a homeowner compensation program.
Key Facts
- Nebraska filed the First Street lawsuit on August 27, 2026 in Dakota County District Court.
- The state challenges First Street’s property-risk marketing, disclosures, underlying data practices and dispute procedures.
- Nebraska alleges that some scores fail to account for property-level protections or otherwise use incomplete or inaccurate information.
- The state is asking the court to stop allegedly unlawful practices, impose civil penalties and require restoration of money allegedly obtained unlawfully.
- First Street has not been found liable, and no court has ordered a homeowner score changed.
- No public homeowner compensation fund or claims portal has been established.
What Happened in the Nebraska First Street Lawsuit
Nebraska Attorney General Mike Hilgers filed a civil lawsuit against First Street on August 27, 2026.
The case was filed in Dakota County District Court after the Attorney General’s Office said homeowners in Nebraska had been harmed by allegedly inaccurate or misleading property-specific climate-risk predictions.
The state’s official announcement says First Street provides property-level scores for hazards such as flooding and wildfire and markets its information as useful for understanding a property’s exposure to climate-related risks.
Nebraska alleges that, for some properties, First Street’s scores rely on incomplete or inaccurate information and do not adequately account for certain flood-protection measures.
The lawsuit remains pending. The allegations have not been established as facts by a judge.
What Nebraska Alleges About First Street’s Risk Scores
The state challenges more than whether two risk models produce different numbers.
According to the complaint and Attorney General’s announcement, Nebraska alleges that First Street:
- uses inaccurate or incomplete information for some properties;
- does not adequately account for some flood-protection investments;
- presents uncertain model predictions in a way consumers may interpret as objective property facts;
- does not sufficiently explain how its results may differ from government data or other climate-risk models;
- withholds portions of its underlying data as proprietary; and
- provides what Nebraska says is an inadequate process for homeowners seeking to dispute an allegedly incorrect score.
Those are Nebraska’s allegations. First Street may dispute the state’s factual and legal claims during the litigation.
First Street’s Position on How Its Scores Work
First Street says its Climate Factor scores are produced through scientific models using multiple forms of historical, geographic and environmental data.
Its Flood Factor methodology, for example, evaluates the probability and potential depth of floodwater reaching a structure over a 30-year period.
Inputs can include rainfall, river flooding, elevation, proximity to water, historic conditions, environmental changes and modeled adaptation measures.
First Street says its models are designed to supplement—not replace—government flood maps.
Why FEMA Maps and First Street Scores Can Differ
A FEMA flood-zone designation and a First Street Flood Factor are not designed to answer exactly the same question.
FEMA flood maps are used for federal floodplain-management purposes and play a role in federal flood-insurance and building requirements.
First Street says Flood Factor instead estimates a property’s broader probability of experiencing flooding over a 30-year period using its own national flood model.
First Street specifically states that a property’s FEMA zone is not used to determine its Flood Factor.
It also states that FEMA maps—not Flood Factor—determine federal flood-insurance and building-code requirements.
For that reason, a difference between a FEMA map and First Street score does not by itself establish that either system is wrong.
The Nebraska lawsuit instead asks whether First Street’s underlying data, representations, disclosures and dispute practices violate Nebraska consumer-protection law.
What Nebraska Says About the Dispute Process
The ability of homeowners to challenge property scores is a significant part of the state’s case.
First Street’s own current property-score dispute policy says that, as a general rule, the company does not update Factor scores in response to individual requests or disputes.
The policy also tells consumers that they should not expect a personalized response when contacting customer support about a score dispute.
First Street lists limited exceptions, including certain FEMA Letter of Map Amendment documentation, base-flood-elevation information and situations involving buildings constructed recently enough that they have not yet appeared in the company’s mapping data.
Nebraska argues that this type of dispute process can leave homeowners without a meaningful way to correct a score when the underlying property information is allegedly wrong.
Property Data Can Change Without Making the Model Itself Invalid
Owners should distinguish between two different types of disputes.
One concerns a factual property characteristic—for example, a structure’s location, elevation, construction date or documented flood-protection measure.
The other concerns disagreement with a model’s estimate of future risk.
A factual error can potentially be supported with records. A disagreement with a model’s methodology or forecast may be more difficult to resolve because different models can use different assumptions, time periods and data sources.
This distinction can become important when documenting a complaint.
What the State Wants From the Court
The Nebraska Attorney General is asking the court to stop practices the state alleges are unfair or deceptive.
The Attorney General’s Office also says Nebraska seeks financial penalties and the return of profits allegedly obtained through unlawful conduct.
The complaint does not establish a fixed dollar amount that individual homeowners would receive.
No restitution checks, consumer claim forms or payment deadlines have been announced.
Any monetary relief for property owners would depend on future court orders, settlement terms or another legally authorized process.
Does the Lawsuit Automatically Remove First Street Scores?
No.
The filing of the lawsuit does not itself require First Street, Zillow or another real-estate platform to remove a particular property’s score.
It also does not automatically:
- change a property’s FEMA flood-zone designation;
- alter a mortgage agreement;
- cancel a flood-insurance requirement;
- change a homeowners-insurance premium;
- establish a property’s market value; or
- prove that a particular buyer rejected a property because of a risk score.
Who May Be Most Directly Affected?
The most directly affected group includes Nebraska homeowners whose First Street risk scores are displayed on, or accessible from, real-estate listing platforms.
A score can also be relevant to buyers, real-estate professionals and others evaluating a property’s potential exposure to flood, wildfire, heat, wind or other hazards.
However, a risk score is only one piece of information that may influence a real-estate transaction.
Owners claiming financial harm should avoid assuming that a First Street score alone caused a lower offer or failed sale unless there is documentation connecting the score with the buyer’s decision.
What Nebraska Homeowners Should Do Now
- Save the current score. Take dated screenshots showing the property address, Factor score, risk category, stated probabilities and explanatory text.
- Preserve the listing. Save the real-estate listing and any link or display showing First Street information.
- Check FEMA information separately. Use the FEMA Flood Map Service Center to identify the applicable flood map and effective date.
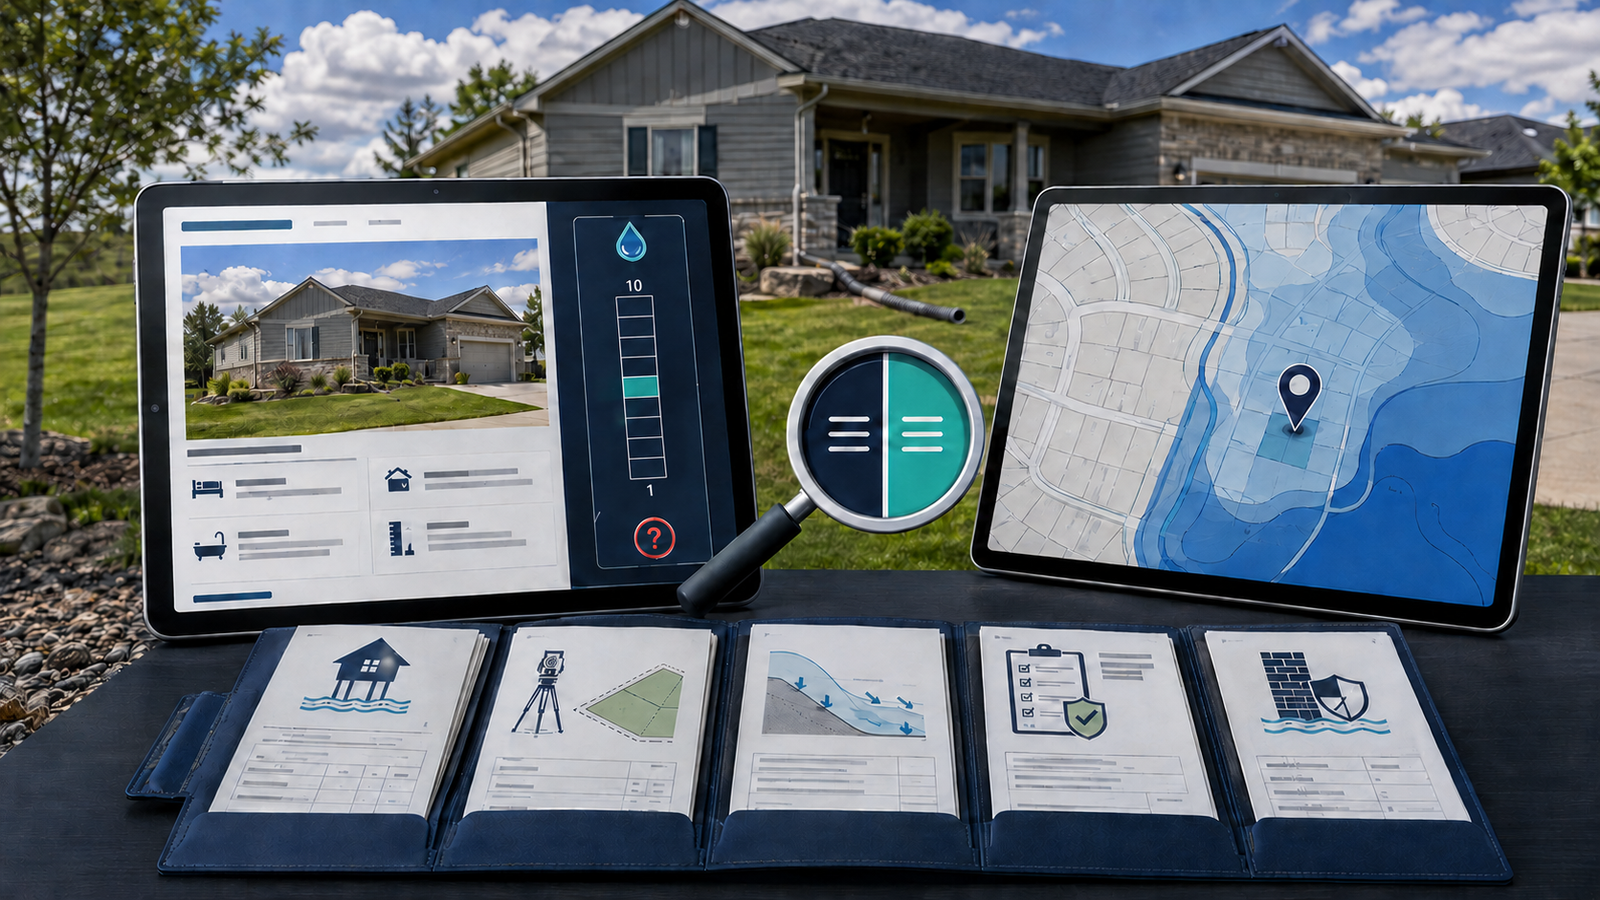
- Gather property-specific documents. Keep elevation certificates, Letters of Map Amendment, surveys, permits, engineering reports and documentation of drainage or flood-control improvements.
- Request a correction where appropriate. Identify the specific factual information believed to be wrong and supply supporting documentation.
- Preserve First Street’s response. Save support tickets, automated messages, emails and other correspondence.
- Document financial effects carefully. Preserve buyer messages, written objections, price reductions, canceled transactions and lender or insurance communications when relevant.
How to Compare a Private Risk Score With FEMA Data
Start by identifying what each source actually measures.
A FEMA map may show whether the property is located within a federally mapped flood-hazard area.
A private model may estimate additional forms of flood exposure and future probability over a longer period.
Record:
- the FEMA map panel number;
- the map’s effective date;
- the property’s mapped flood zone;
- the First Street Flood Factor;
- the probability and time period shown by First Street; and
- any property-specific mitigation measures that may not appear accurately in one of the data sets.
These records make a dispute more specific than simply saying that two scores disagree.
What if a Risk Score Affects Insurance?
If an insurance company changes a premium, eligibility decision, underwriting classification or coverage based on property-risk information, ask the insurer for an explanation in writing.
Do not assume the Nebraska lawsuit automatically invalidates the insurer’s decision.
Consumers with unresolved insurance issues can use the Nebraska Department of Insurance complaint process.
Nebraska DOI says its Insurance Complaint Division can review whether an insurer or agent complied with Nebraska insurance law and can request an explanation from the company.
The Department cannot act as a court, provide legal representation, establish a property’s value or automatically order an insurer to pay a claim or issue a refund.
How to Report a Consumer-Protection Concern
A Nebraska property owner who believes inaccurate information or an unfair dispute process caused harm can use the Nebraska Attorney General’s consumer complaint process.
A useful complaint should describe the alleged error clearly and include supporting records such as screenshots, property documentation, correspondence and evidence of any claimed financial impact.
Submitting a complaint does not guarantee individual representation, correction of a First Street score or financial compensation.
Nebraska First Street Lawsuit FAQ
Has First Street been found liable?
No. Nebraska filed a civil complaint on August 27, 2026. The allegations remain subject to litigation.
Does the lawsuit mean First Street scores are invalid?
No. The filing does not invalidate every First Street score. Nebraska is asking a court to determine whether particular business practices violated state consumer-protection law.
Can a homeowner force First Street to change a score?
First Street currently says it generally does not update Factor scores based on individual disputes. It identifies limited exceptions involving certain FEMA documentation and recently constructed properties.
Does a FEMA flood zone override Flood Factor?
The two systems measure risk differently. First Street says FEMA zone designations do not determine Flood Factor, while FEMA maps remain the relevant system for federal flood-insurance and building-code requirements.
Is there a homeowner compensation fund?
No public claims portal, fixed restitution fund or homeowner payment deadline has been announced.
What should an owner preserve?
Keep dated screenshots, FEMA map records, elevation or mitigation documentation, correspondence with First Street, listing information and any evidence showing how the disputed information allegedly affected a transaction.
Bottom Line
The Nebraska First Street lawsuit asks a state court to decide whether First Street’s marketing, property data, climate-risk disclosures and consumer dispute procedures violate Nebraska consumer-protection laws.
The Attorney General alleges that some homeowners have been harmed by inaccurate or misleading property-level predictions. First Street, however, describes its Climate Factor scores as model-based risk assessments and explains that its flood scores serve a different purpose from FEMA flood-zone maps.
No liability, score-removal order or homeowner compensation program has been established.
Nebraska property owners concerned about a score should preserve the existing listing and score, compare it with official property and FEMA records, document any factual error and financial effect, and use verified complaint channels when appropriate.
How We Verified This Report
Jurisdiction: Nebraska, United States
Case status: Civil complaint filed; no liability determination announced
Official action date: August 27, 2026
Last fact-checked: September 1, 2026
Primary and First-Party Sources
- Nebraska Attorney General — August 27, 2026 First Street lawsuit announcement
- Nebraska Attorney General — First Street Court Complaint
- First Street — Property Score Dispute Policy
- First Street — Flood Factor Methodology
- FEMA — Flood Map Service Center
- Nebraska Department of Insurance — Consumer Complaint Process
Editorial Review
This report distinguishes Nebraska’s allegations from established findings and explains that FEMA flood mapping and First Street’s modeled Climate Factor scores serve different purposes. It does not treat disagreement between two risk systems as proof that either system is necessarily incorrect.
Important Information
This article provides general consumer information and is not individualized legal, insurance, real-estate or financial advice. Disclosure duties, property valuation, insurance requirements and available remedies depend on the property, transaction, policy, evidence and applicable law.
Official Source Stack
Direct sources supporting the material claims in this report.
- Court filing or order 63-page complaint against First Street
- Official agency release Nebraska attorney general’s August 27 announcement
- Official agency release FEMA Flood Map Service Center
- Official agency release Nebraska attorney general’s consumer complaint form
This report provides general news and educational information for a U.S. audience. It is not individualized financial, credit, legal, tax, insurance or investment advice. Verify current procedures through the linked official sources.