Published: August 16, 2026
Updated: October 1, 2026
Last fact-checked: October 1, 2026
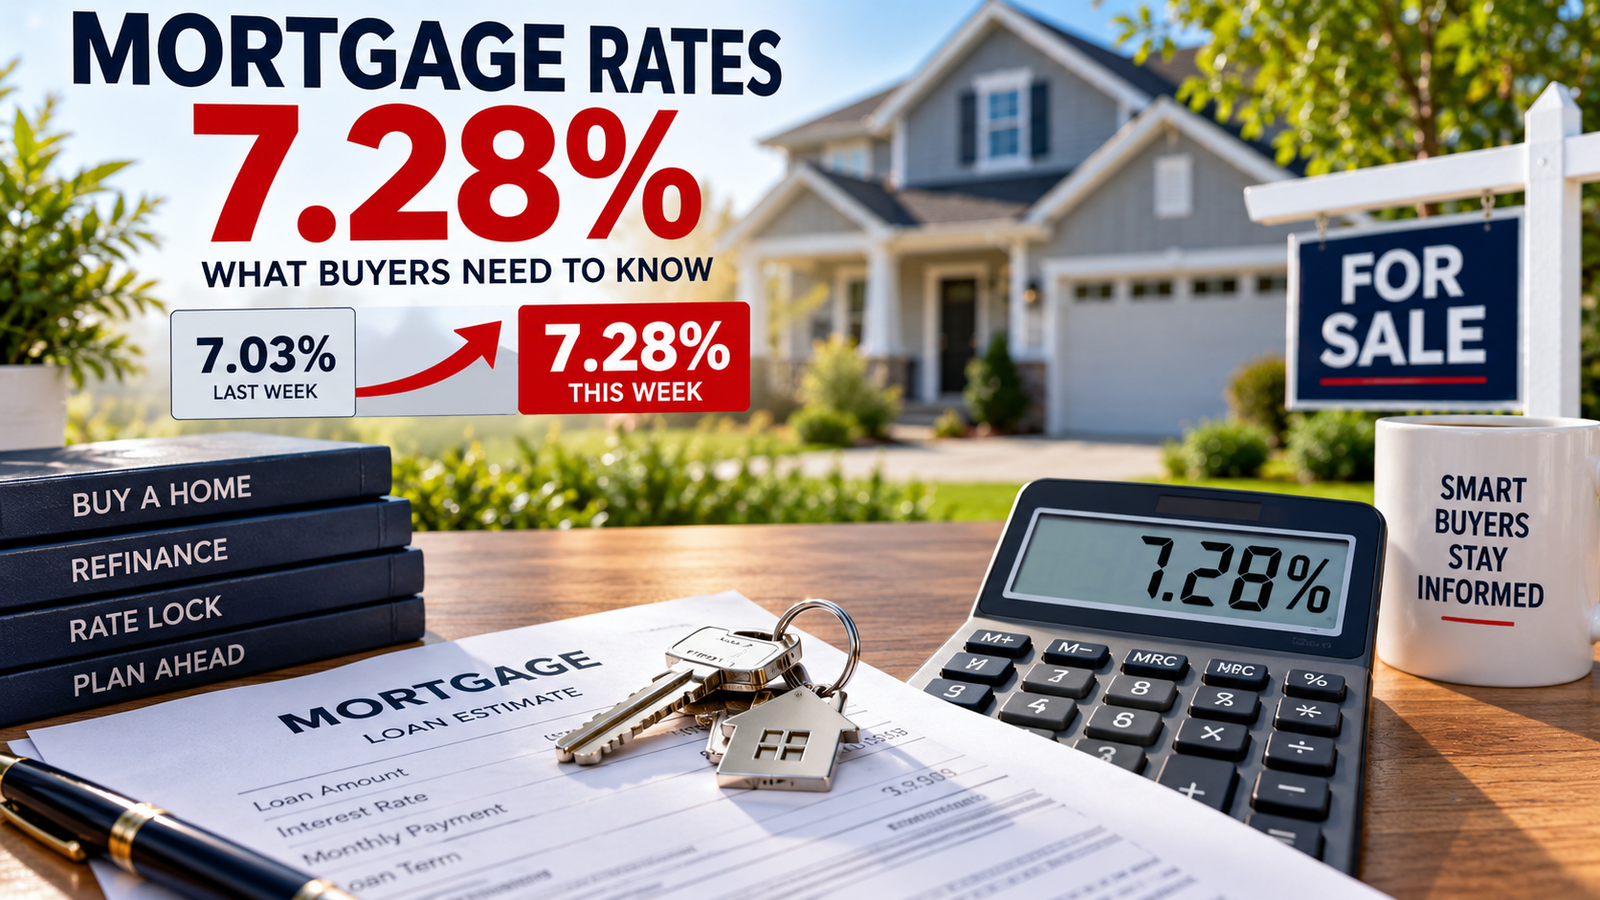
Current status: Freddie Mac’s October 1, 2026 PMMS average is 7.28% for a 30-year fixed-rate mortgage and 6.60% for a 15-year fixed-rate mortgage.
Mortgage rates 7.28% is the latest national benchmark from Freddie Mac after the 30-year fixed average rose from 7.03% one week earlier. That 25-basis-point increase can materially change the principal-and-interest payment on a new mortgage, but it does not change an existing fixed-rate loan and is not a guaranteed quote. Buyers should compare actual Loan Estimates, APRs, points, fees and rate-lock terms.
Key Facts
- The 30-year fixed average was 7.28% on October 1, up from 7.03% on September 24.
- The weekly increase was 0.25 percentage point, or 25 basis points.
- The 15-year fixed average rose to 6.60% from 6.42%.
- A year earlier, the 30-year average was 6.34%.
- PMMS focuses on conventional, conforming, fully amortizing purchase loans for borrowers with 20% down and excellent credit.
What the latest mortgage rates show
Freddie Mac announced the October 1 results in its Primary Mortgage Market Survey release. The 30-year fixed average increased to 7.28%, while the 15-year fixed average increased to 6.60%.
The 30-year rate is also 94 basis points above the 6.34% reading from the comparable week of 2025. That comparison describes a national benchmark, not the change in any individual household’s mortgage payment.
What Mortgage Rates 7.28% Mean for New Payments
This illustrative calculation compares the September 24 average of 7.03% with the October 1 average of 7.28% for a fully amortizing 30-year fixed loan.
| Loan amount | Payment at 7.03% | Payment at 7.28% | Monthly increase |
|---|---|---|---|
| $300,000 | $2,001.96 | $2,052.64 | $50.68 |
| $400,000 | $2,669.27 | $2,736.85 | $67.58 |
| $500,000 | $3,336.59 | $3,421.06 | $84.47 |
Calculation method: payment = principal × monthly rate × (1 + monthly rate)360 ÷ ((1 + monthly rate)360 − 1), using Freddie Mac’s weekly averages as the annual rates. For a $400,000 loan, the weekly move adds about $67.58 per month, or about $810.96 over 12 months if the rate and balance are otherwise identical.
Compared with the 6.34% year-ago benchmark, the same $400,000 illustration is about $250.52 higher per month at 7.28%. These examples exclude points, lender fees, mortgage insurance, taxes, homeowners insurance and association dues. They do not establish an individual borrower’s payment.
What Freddie Mac’s 7.28% average measures
Freddie Mac’s PMMS methodology and FAQs say the survey uses mortgage-rate data from thousands of applications submitted through Loan Product Advisor by lenders nationwide. It is a weekly average, not a single-day quote.
The benchmark focuses on conventional, conforming, fully amortizing purchase loans for borrowers with 20% down and excellent credit. Freddie Mac does not publish average fees and points because that information is not consistently supplied under the current data process.
Borrower-specific offers can differ with credit, down payment, loan size, property, location and lender pricing. FHA, VA, USDA, jumbo and adjustable-rate products are not represented by this 30-year conventional fixed-rate benchmark.
Who is affected by the weekly increase?
Homebuyers currently applying for conventional fixed-rate purchase loans are the most directly exposed. Buyers without a rate lock can see lender pricing move before closing.
Existing homeowners with fixed-rate mortgages do not get a higher contractual rate because the weekly average rose. Refinancing requires a new loan, and refinance pricing should be compared separately rather than assuming 7.28% is the available refinance rate.
What buyers should compare now
- Request Loan Estimates from multiple lenders for the same loan type, amount and lock period.
- Compare the rate with APR, points, origination charges, lender credits and cash to close.
- Check whether the rate is locked and the date the lock expires.
- Ask what an extension costs if closing moves beyond the lock period.
- Keep Loan Estimates, revised estimates, rate-lock agreements and lender communications.
The CFPB’s loan-comparison guide recommends comparing multiple Loan Estimates, including payments, mortgage insurance, upfront loan costs, lender credits and cash to close. Its mortgage rate-lock guidance explains when a locked rate can remain unchanged before closing.
What has not changed
- The 7.28% average does not reset an existing fixed-rate mortgage.
- It does not guarantee that a new applicant will receive 7.28%.
- It does not establish points, lender fees, taxes or insurance costs.
- It does not predict whether rates will rise or fall next week.
What would require another update?
This report should be updated when Freddie Mac publishes its next PMMS result or materially changes the survey methodology. A material change in CFPB mortgage-shopping guidance could also justify an update.
Bottom line
The October 1 Freddie Mac reading moves the 30-year fixed benchmark to 7.28%, 25 basis points above the prior week. On an illustrative $400,000 30-year loan, that difference is about $67.58 per month in principal and interest. The practical response is to compare complete lender offers rather than treat the national average as a personalized quote.
Editorial disclaimer: Fiscal Wire News provides general financial-news and educational information, not individualized mortgage, financial, tax, insurance, legal or investment advice. Mortgage rates and loan terms vary by borrower, lender and transaction.
Official Source Stack
Direct sources supporting the material claims in this report.
- Official agency release CFPB's loan-comparison guide
- Official agency release mortgage rate-lock guidance
This report provides general news and educational information for a U.S. audience. It is not individualized financial, credit, legal, tax, insurance or investment advice. Verify current procedures through the linked official sources.